Real Estate Consortium in Brazil: How to Connect the Credit Letter, Construction and Cash Flow
A real estate consortium may be assessed as one possible component of a development’s funding structure. The decisive question is not whether the credit letter…
Imovitec · September 02, 2026
A real estate consortium may be assessed as one possible component of a development’s funding structure. The decisive question is not whether the credit letter has an attractive face value. A finance director must determine whether its documented conditions, the physical progress of construction and the project’s payment obligations can be synchronized.
Expected credit and available liquidity are different categories. Confusing them may create a cash mismatch when contractors, suppliers or other obligations must be paid.
Key takeaways
A consortium credit letter should remain a conditional resource in the project model until its permitted use, requirements and timing are supported by current rules and binding documents. The supplied evidence confirms one historical publication by Banco Central do Brasil, but it does not establish the present regulatory or operational conditions for a specific transaction.
- Place contractual events, construction milestones and payments on one dependency map.
- Confirm operational assumptions using current official rules and the administrator’s binding documents.
- Do not presume release procedures, payees, guarantees, documents or review periods.
- Exclude unsupported amounts, percentages, indices and deadlines from the investment case.
- Approve the structure only after reconciling documented funding conditions with the construction cash flow.
What does an integrated consortium funding system mean?
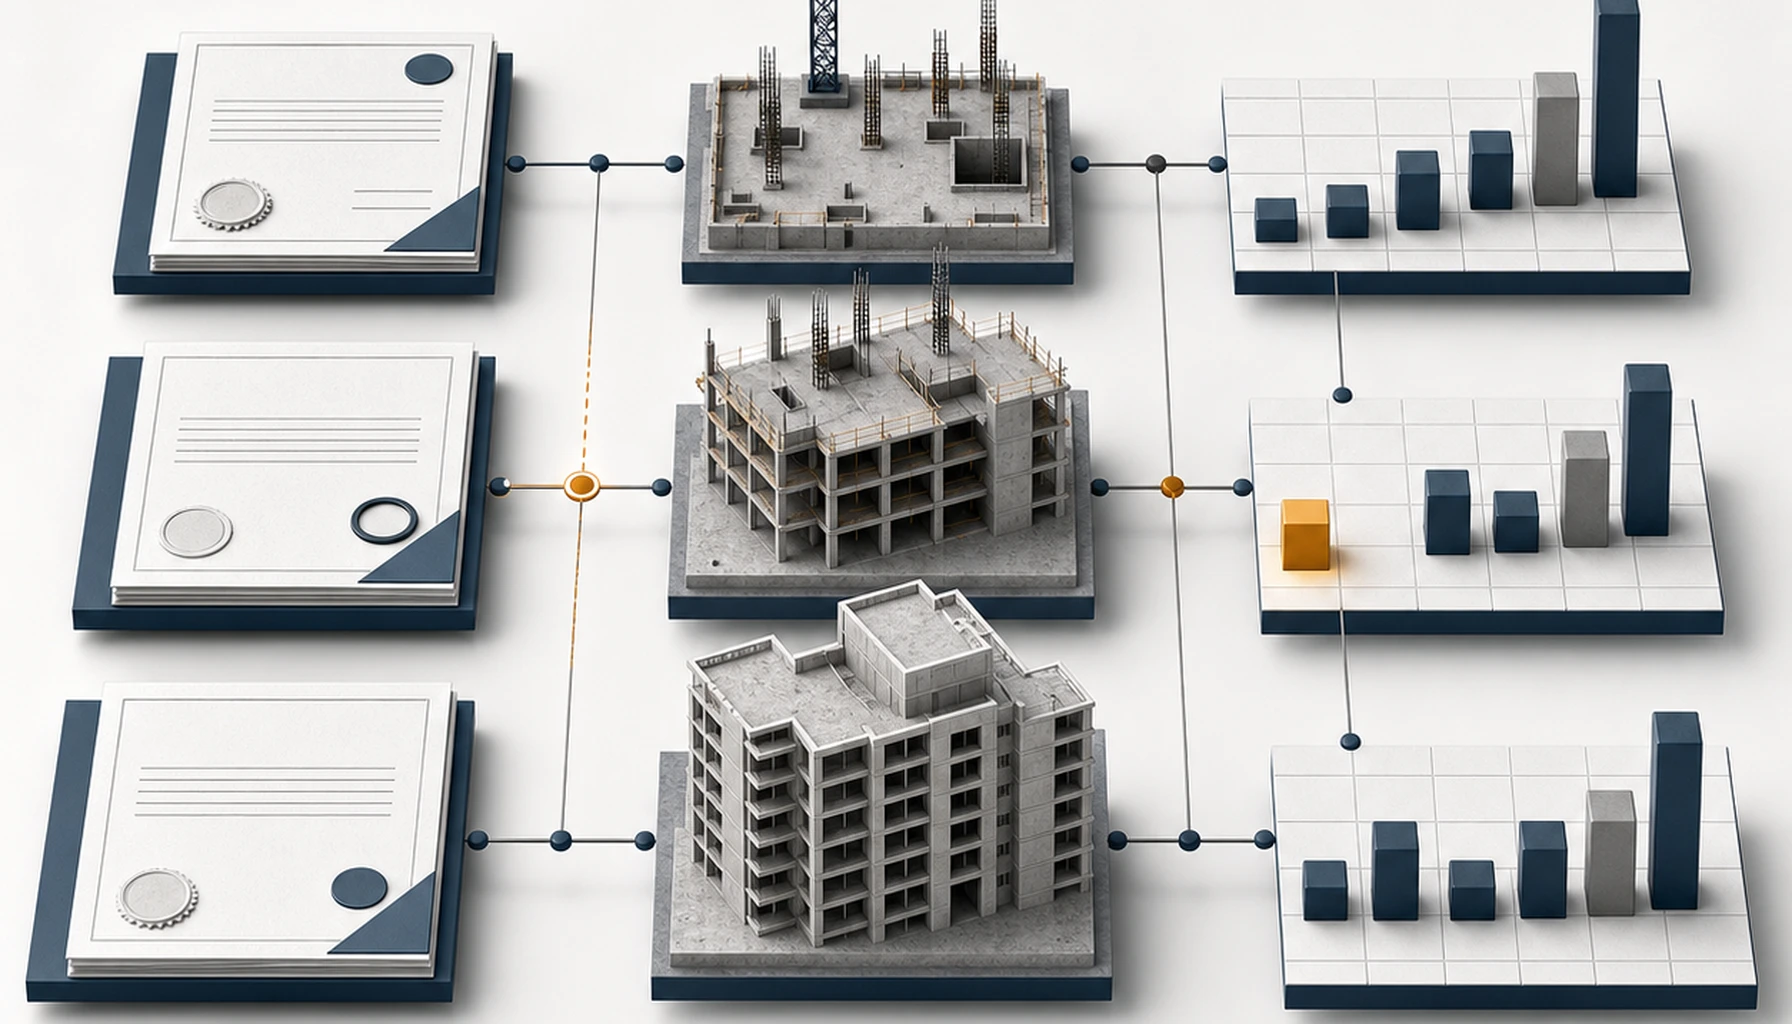
An integrated system connects each expected funding source to the condition that makes it usable, then connects every construction payment to a due date and confirmed source. It combines contractual, physical and financial dependencies without presuming that a credit letter is unrestricted cash or that one process applies to every administrator.
Concise definition: An integrated funding system links credit conditions, construction milestones and payment dates in one dependency map.
The model has three layers:
- Contractual: events, approvals, documents and conditions related to the credit.
- Physical: milestones derived from the project’s technical plan.
- Financial: payment dates, committed expenditures and documented liquidity sources.
This structure is a planning method, not a regulatory conclusion. Whether a particular consortium can support acquisition, construction or renovation remains unknown in the approved evidence package. That point requires confirmation under current official rules, the contract and the administrator’s group regulations.
Why is a credit letter different from project cash?
A credit letter and available cash should remain separate categories until applicable rules and contractual documents establish how, when and for which obligation the credit can be used. The approved research did not verify payment mechanics, release procedures, guarantees or exceptions, so the project model cannot treat those details as established facts.
The practical question is precise: under which documented conditions can this resource satisfy this obligation on this date?
The following propositions remain unknown in the supplied evidence:
- whether contemplation occurs through a draw or bid;
- whether an index adjusts the credit;
- whether the administrator analyzes the transaction or requires guarantees;
- whether payment goes to a seller, contractor or supplier;
- whether construction funding is released in stages after measurement or inspection;
- whether cash may be received after obligations and a statutory period are satisfied.
Each answer could change the liquidity profile. Until verified, the related amount should appear as conditional, not available.
How should the three timelines be connected?
Begin with three parallel timelines covering contractual events, physical milestones and financial obligations. Connect the items that must happen in sequence, identify the evidence supporting each connection and assign responsibility for unresolved questions. Any payment that precedes a confirmed funding event exposes a potential mismatch requiring further review.
Timeline 1: credit conditions
Record only conditions supported by current official rules and the administrator’s documents. For each item, identify the source, applicable provision or clause, responsible reviewer and unresolved question. Market custom cannot fill an evidence gap.
Banco Central do Brasil published Circular No. 3,432 on February 3, 2009, concerning the formation and operation of consortium groups. The official PDF is available from Banco Central do Brasil. The supplied research did not establish its current validity, amendments, revocation, consolidation or relationship with Resolution BCB No. 285/2023. It must not be presented as the current governing rule without regulatory review.
Timeline 2: physical construction
Derive milestones from the project’s technical documents. The approved evidence does not validate a universal sequence of construction stages or a standard list of required records.
Claims that property registration, permits, ART or RRT records, budgets and schedules are always mandatory are blocked. Requirements may vary by municipality, project, administrator, contract and transaction. The technical team should establish project needs, while legal and contractual reviewers confirm funding requirements.
Timeline 3: payments and liquidity
List each documented obligation with its amount basis, due date and intended source. Separate committed liquidity from conditional resources. Do not insert estimates for bids, fees, reserve funds, insurance, indexation, release percentages or deficits without validated evidence.
The same discipline belongs in a broader real estate feasibility study. Land, product, construction and funding assumptions should remain traceable instead of allowing one optimistic funding premise to shape the entire project.
How can a developer identify a cash mismatch before contracting?
A cash mismatch exists when a documented payment becomes due before its intended funding source is demonstrably usable. Detection requires dates, conditions and dependencies. A nominal credit amount alone cannot show whether the project can meet a particular obligation when that obligation falls due.
Use a reconciliation table during exploration:
| Decision field | Required evidence | Treatment while missing |
|---|---|---|
| Intended use of credit | Current official rule and administrator documents | Mark as unknown |
| Trigger for use | Applicable contractual and regulatory provisions | Treat the resource as conditional |
| Review process | Written administrator criteria | Assign no assumed deadline |
| Guarantees | Confirmed transaction requirements | Do not presume acceptance |
| Release schedule | Written schedule applicable to the project | Do not match it to construction yet |
| Construction payment | Contract, budget and physical-financial schedule | Record the actual obligation |
| Backup liquidity | Approved, documented source | Exclude informal possibilities |
No numerical simulation is included because the approved package contains no validated calculation. A defensible simulation would require documented inputs, a reproducible formula, consistent units and periods, an explicit policy for missing data and a stated rounding method. Without them, a precise deficit would be invented.
Which evidence must be confirmed before a decision?
The required evidence is the set needed to close every material dependency between credit use and project payments. It should combine regulatory, contractual, financial and technical review. No universal checklist can be inferred from the supplied research because requirements may differ by administrator, contract, municipality, project and transaction.
Regulatory and legal review
Confirm the current text and applicability of Law No. 11,795/2008, Resolution BCB No. 285/2023, subsequent amendments and the status of Circular No. 3,432/2009. Review the legal basis for credit use, guarantees, payment mechanics and any conditions for receiving cash. This article does not resolve those questions.
Administrator review
Obtain the contract, group regulations and written operational criteria. Confirm permitted uses, analysis procedures, guarantees, required documents, payment recipients, release conditions and applicable periods. Separate general legal requirements from the administrator’s contractual policy.
3,432 on February 3, 2009, concerning the formation and operation of consortium groups.
Financial review
Validate the adjustment mechanism, administration fee, reserve fund, insurance, bid assumptions, default consequences and potential cash gaps. None of these variables was verified in the supplied research. They must remain outside the approved model until documented.
Technical review
Reconcile the complete budget, physical-financial schedule, applicable licenses, professional responsibility records and any measurement or inspection process actually required. SINAPI or CUB should not be treated as automatic substitutes for a complete project budget without a documented method and appropriate adjustments.
FGTS review
Do not presume that FGTS may fund a bid, supplement, amortization or settlement. These possibilities remain unknown in the approved package. Check the current FGTS Home Ownership Use Manual and rules issued by the competent entities.
Talk to a specialist
Want to see this applied to your case?
Instead of finishing the article and staying in theory, send us your situation on WhatsApp. We reply with the concrete next step.
What should the approval gate test?
The approval gate should test whether documented evidence connects the intended credit use to the project’s actual payment schedule. Approval should not depend on nominal value alone. Unresolved conditions must remain visible as unknowns, while any timing still subject to approval requires a documented source of backup liquidity.
The finance director, planning manager or project lead should be able to answer:
- Is the intended use expressly supported by current rules and contractual documents?
- Are the conditions for use and required guarantees documented?
- Has the operational process been confirmed in writing?
- Can the construction schedule tolerate the documented timing?
- Does every material payment have a confirmed source?
- Are open issues shown as unknowns rather than hidden assumptions?
- Is approved backup liquidity documented where timing remains conditional?
Inputs change. The control must change with them. This resembles the discipline used to monitor weekly market data for real estate developers: each input should retain its source, date, scope and limitation.
Can a consortium support a coherent construction funding plan?
Potentially, but the approved evidence is insufficient to confirm that conclusion for any specific product or project. Suitability depends on current regulation, the administrator’s binding documents, transaction criteria, the technical plan and a reconciled payment schedule. Nominal credit value and unverified market practice cannot establish funding readiness.
The operating standard is simple. Credit enters the model only to the extent that its intended use, conditions and timing are evidenced. Everything else remains conditional.
Managing the three timelines together helps the development team distinguish confirmed resources, approval-dependent resources and unresolved questions before committing to payments.
Source and evidence limitations
The only verified material fact in the approved source package is that Banco Central do Brasil published Circular No. 3,432 on February 3, 2009, concerning the formation and operation of consortium groups. No market statistic, operational rule or material calculation was validated for publication.
Source: Banco Central do Brasil, Circular No. 3,432, of February 3, 2009, official PDF, Brazil, published February 3, 2009, accessed September 2, 2026: official document.
Limitation: The research did not verify operative provisions, current validity, amendments, revocation, consolidation or replacement. Other regulatory, contractual, financial and technical propositions discussed above remain unknown or blocked pending review.
FAQ
How do I spot the catch in a Brazilian real estate consortium?
The main risk is treating a conditional credit letter as unrestricted cash. Before including it in construction funding, verify the current official rules, administration agreement, fees, adjustment terms, contemplation conditions, guarantees, permitted uses and disbursement schedule. Compare those requirements with the project’s documented payment dates and liquidity needs.
Can a consortium credit letter replace or pay off construction financing?
A credit letter should not be assumed to replace or settle financing automatically. Eligibility depends on current regulations, the consortium agreement, the administrator’s approval and the existing lender’s conditions. Obtain written confirmation of the permitted transaction, required guarantees, payment destination and timing before changing the project’s capital structure.
How do I turn a consortium credit letter into money for my construction project?
A consortium credit letter must remain classified as conditional credit until its use and availability are documented. Do not model it as free cash based on expected contemplation alone. Confirm whether cash receipt or third-party payment is permitted under current rules and the contract, then align the verified process with construction obligations.
How does a real estate consortium work for construction or renovation?
A construction consortium combines periodic contributions with access to credit subject to contemplation and documented use conditions. Whether it covers construction or renovation, and how funds are released, must be confirmed in current official rules and the administrator’s contract. The financial model should reflect only verified milestones, requirements and payment flows.
What’s the best way to connect the credit letter, construction schedule and cash flow?
The best method is a single physical-financial schedule linking every construction milestone to its invoice, due date, funding source and release condition. Record the credit letter as conditional until all requirements are confirmed. Stress-test delays and maintain a documented alternative funding source for obligations due before any verified disbursement.
Is a real estate consortium cost-effective for a developer or construction company?
Cost-effectiveness can be determined only by comparing complete, documented cash flows. Include administration fees, reserve funds, insurance, contractual adjustments, bid funding, guarantees, timing risk and backup liquidity, where applicable. No material simulation is supportable without verified inputs. Compare alternatives using the same horizon, assumptions and reproducible formulas.
What evidence makes a consortium credit letter reliable enough for a project budget?
Reliable budgeting requires current official regulations, the administrator’s binding agreement and rules, contemplation and use conditions, guarantee criteria, a confirmed disbursement schedule, complete construction budget and documented physical-financial plan. Any unresolved term should remain an explicit assumption or risk, not be converted into available liquidity in the base-case forecast.
Related reading
Talk to a specialist
Have a real case to solve?
Message Imovitec on WhatsApp. We reply fast and already speak your context — no forms, no waiting.
Frequently asked questions
How do I spot the catch in a Brazilian real estate consortium?
The main risk is treating a conditional credit letter as unrestricted cash. Before including it in construction funding, verify the current official rules, administration agreement, fees, adjustment terms, contemplation conditions, guarantees, permitted uses and disbursement schedule. Compare those requirements with the project’s documented payment dates and liquidity needs.
Can a consortium credit letter replace or pay off construction financing?
A credit letter should not be assumed to replace or settle financing automatically. Eligibility depends on current regulations, the consortium agreement, the administrator’s approval and the existing lender’s conditions. Obtain written confirmation of the permitted transaction, required guarantees, payment destination and timing before changing the project’s capital structure.
How do I turn a consortium credit letter into money for my construction project?
A consortium credit letter must remain classified as conditional credit until its use and availability are documented. Do not model it as free cash based on expected contemplation alone. Confirm whether cash receipt or third-party payment is permitted under current rules and the contract, then align the verified process with construction obligations.
How does a real estate consortium work for construction or renovation?
A construction consortium combines periodic contributions with access to credit subject to contemplation and documented use conditions. Whether it covers construction or renovation, and how funds are released, must be confirmed in current official rules and the administrator’s contract. The financial model should reflect only verified milestones, requirements and payment flows.
What’s the best way to connect the credit letter, construction schedule and cash flow?
The best method is a single physical-financial schedule linking every construction milestone to its invoice, due date, funding source and release condition. Record the credit letter as conditional until all requirements are confirmed. Stress-test delays and maintain a documented alternative funding source for obligations due before any verified disbursement.
Is a real estate consortium cost-effective for a developer or construction company?
Cost-effectiveness can be determined only by comparing complete, documented cash flows. Include administration fees, reserve funds, insurance, contractual adjustments, bid funding, guarantees, timing risk and backup liquidity, where applicable. No material simulation is supportable without verified inputs. Compare alternatives using the same horizon, assumptions and reproducible formulas.
What evidence makes a consortium credit letter reliable enough for a project budget?
Reliable budgeting requires current official regulations, the administrator’s binding agreement and rules, contemplation and use conditions, guarantee criteria, a confirmed disbursement schedule, complete construction budget and documented physical-financial plan. Any unresolved term should remain an explicit assumption or risk, not be converted into available liquidity in the base-case forecast.
Imovitec
Turn data into next steps.
Take the Imovitec diagnostic and see where your best opportunities are.