Adjusted Outstanding Balance in an Off-Plan Assignment: How to Calculate What the Seller Keeps
When an off-plan property has not been fully paid, the advertised assignment price does not necessarily equal the amount the seller receives. A defensible…
Imovitec · October 12, 2026
When an off-plan property has not been fully paid, the advertised assignment price does not necessarily equal the amount the seller receives. A defensible estimate must reconcile the negotiated price, the outstanding balance on the proposed closing date, and every documented expense allocated to the seller.
Two results matter. First, calculate the gross assignment amount. Then deduct verified seller expenses to estimate pre-tax net cash. Neither result is automatically the seller’s taxable capital gain, which requires a separate assessment based on tax records and the rules applicable on the transaction date.
Key takeaways
A safe assignment estimate uses one closing date, an official debt statement, and documented cost allocation. Price, debt, and expenses must not come from different reference dates. If a contractual rule or essential document is missing, the affected result should remain pending rather than being replaced by a generic percentage.
- Use the same reference date for the negotiated price and outstanding balance.
- Obtain the contract and an official statement from the developer or creditor. An old payment slip is insufficient.
- Calculate gross assignment proceeds separately from pre-tax net cash.
- Do not presume that INCC applies. The contract controls the index, variant, reference periods, lag, and application method.
- Do not describe closing cash as profit or taxable gain.
- Block the estimate when essential data cannot be verified.
What is an assignment with an adjusted outstanding balance?
An assignment transfers contractual purchase rights before the property has been fully paid. In the transaction examined here, the incoming buyer assumes or settles the remaining balance, subject to the creditor’s consent and the assignment documents. The exact legal structure must be confirmed for each transaction.
Concise definition: An adjusted balance is the debt recognized by the creditor for a specified date after contractual payments, indexation, and charges are applied.
The City of São Paulo describes the assignment of rights arising from a promise or commitment to purchase and sell. That municipal guidance supports the basic transaction mechanics, but it does not establish a nationwide tax rule or replace the contract. See the City of São Paulo guidance on assignment of purchase rights, accessed October 12, 2026.
For the wider transaction flow, read Off-Plan Assignment in Brazil: Step-by-Step Process and Costs.
How do you calculate what remains for the seller?
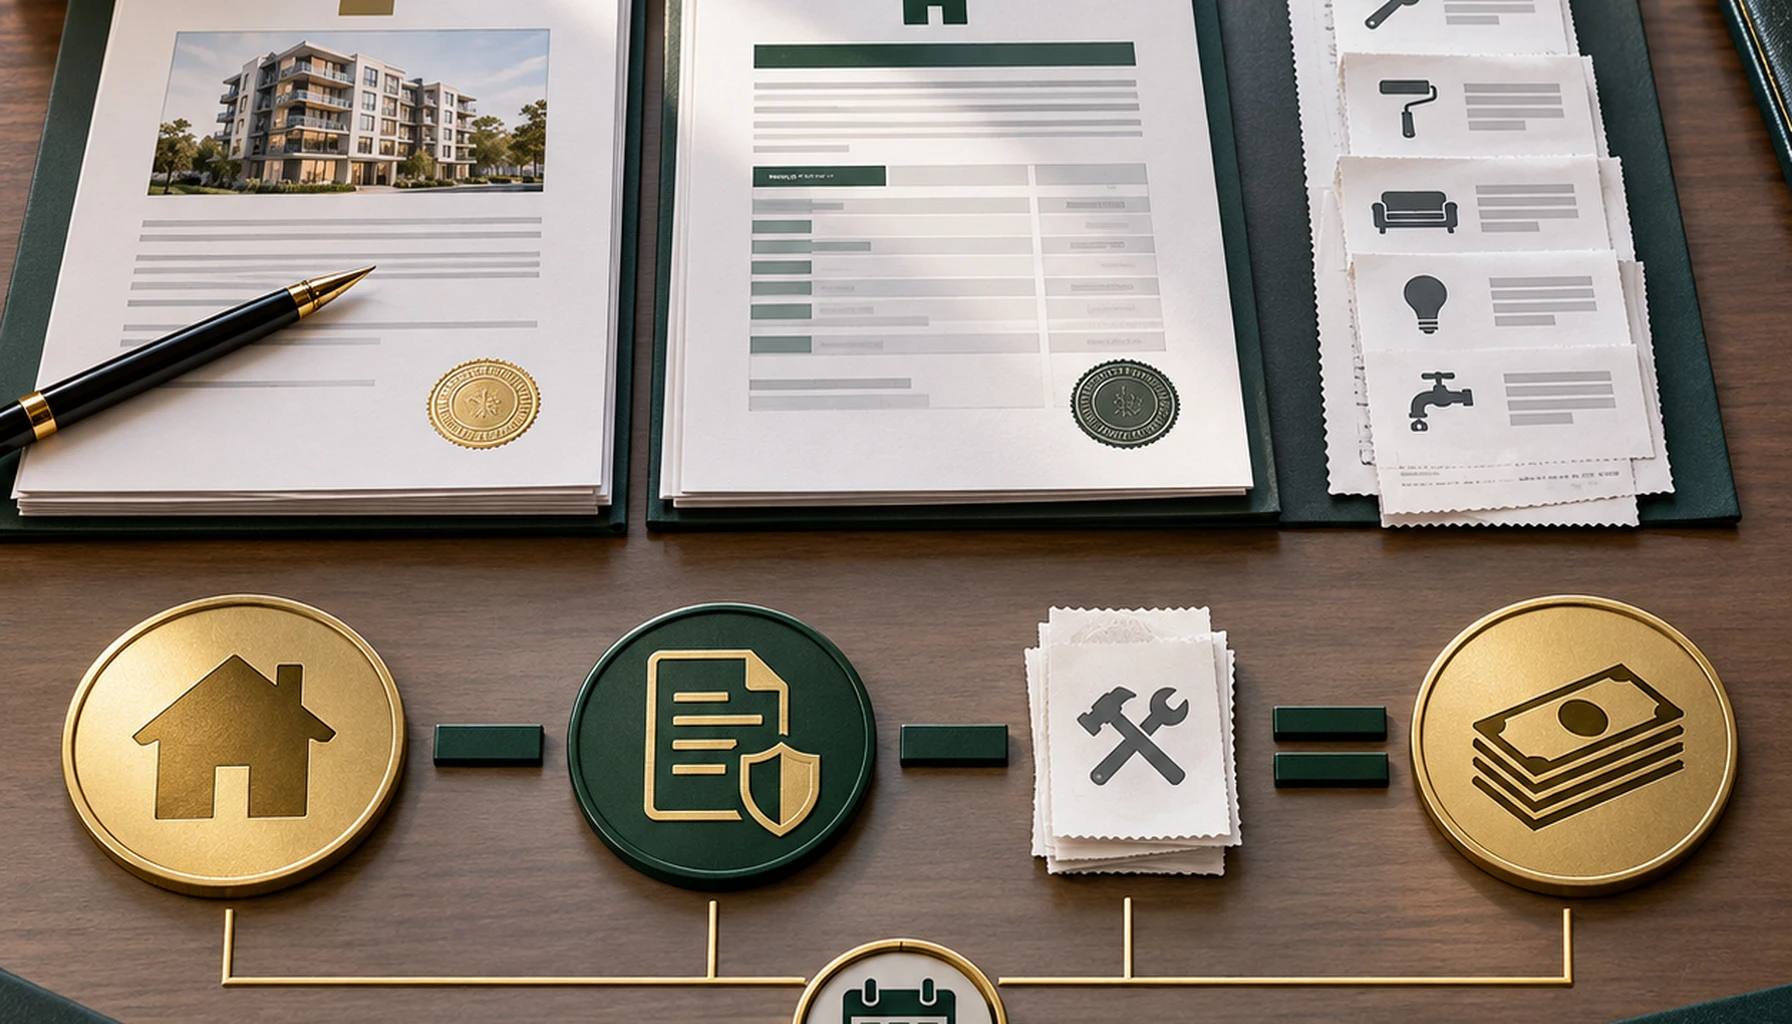
As an operational estimate, gross assignment proceeds equal the total price negotiated for the rights minus the updated balance assumed or settled by the buyer. Pre-tax net cash equals that gross amount minus documented expenses and debts allocated to the seller. These are accounting inferences, not universal legal formulas.
| Result | Calculation | Required evidence |
|---|---|---|
| Gross assignment proceeds | Negotiated price P minus updated balance S | Assignment instrument and official balance statement for the same closing date |
| Pre-tax net cash | P minus S minus documented seller deductions D | The same P and S, plus contracts, invoices, receipts, and relevant debt statements |
All three amounts use Brazilian reais and one transaction as the denominator. The measurement period ends on the proposed closing date. Preserve the creditor’s intermediate decimal treatment and round the displayed result to cents only at the end, unless the contract or official statement requires another method.
A reproducible sequence
- Set the proposed closing date.
- Record the total price negotiated for the contractual rights.
- Request an official debt statement for that date.
- Reconcile overdue installments, interest, penalties, insurance, and separately identified charges.
- Confirm whether the buyer assumes the debt or whether closing funds will settle it.
- List only costs demonstrably allocated to the seller.
- Calculate gross proceeds and pre-tax net cash separately.
- Keep income tax outside this worksheet until the tax review is complete.
If P, S, or D is unavailable, do not manufacture a numerical result. Mark the missing input as pending.
Why can the balance differ from the nominal unpaid installments?
The updated balance may differ because contractual correction, charges, and payments occur on different dates. A reproducible calculation applies the agreed rule to each obligation and deducts each payment on the specified date and in the contractual order. Applying one accumulated index to an old balance may therefore be incorrect.
When the contract uses monthly index variations, the abstract accumulated correction factor is the product of one plus each applicable monthly variation. Required inputs are the official series for the contracted variant, the contractual base date, each reference month, the lag, and the correction clause.
This factor is dimensionless. Its period runs from the contractual base date to the statement date. Rounding occurs only at the end, subject to the contract or creditor’s statement. Missing variants, periods, or lag rules block the calculation.
Intermediate payments require an obligation-by-obligation reconciliation in reais. Each payment must be allocated on the date and in the order required by the agreement. When that process cannot be reproduced, request the creditor’s calculation statement instead of estimating a future index.
Law 13,786 of December 27, 2018 addresses contract termination for default in real-estate developments and land subdivisions.
Does every off-plan balance use INCC?
No. The contract determines whether an INCC variant or another indicator applies, which periods enter the calculation, what lag is used, and whether the index changes after completion, an occupancy permit, or financing. No supplied source supports treating INCC as a universal adjustment rule for off-plan balances.
Fundação Getulio Vargas’s Brazilian Institute of Economics, FGV IBRE, defines INCC as an indicator of changes in residential construction costs. It is currently calculated from information collected in seven Brazilian capitals. It is not a property sale-price index and does not independently determine how a contract adjusts installments. See FGV IBRE’s institutional INCC page, accessed October 12, 2026.
FGV IBRE also states that the weighting structure was updated using analytical budgets for residential projects carried out from 2018 through 2022, with direct collection of labor costs. This methodological fact supports checking the exact index variant, but it does not validate a specific contract calculation. Consult the FGV IBRE announcement and its methodology repository, both accessed October 12, 2026. The announcement’s full publication date was not confirmed in the supplied research.
Which expenses should be deducted from the seller’s proceeds?
Deduct an expense only when the contract, current developer schedule, invoice, receipt, debt statement, or applicable legal review shows that the seller bears it. There is no verified universal list or generic percentage. Responsibility, calculation base, amount, and supporting evidence must be checked line by line.
Possible review items include an assignment fee, brokerage, outstanding debts, and applicable taxes. Their appearance on a checklist does not establish that the seller owes them. ITBI, registration charges, consent costs, brokerage, and income tax must never be allocated automatically.
A closing worksheet should contain:
- item and description;
- responsible party;
- contractual or legal basis;
- calculation base;
- verified amount in reais;
- supporting document;
- status: confirmed, pending, or excluded.
The denominator is one transaction, and the relevant period is the closing plus directly related expenses. Display final amounts in cents. Keep every unverified entry pending instead of importing a customary percentage from another development.
The same evidence standard applies when assessing the total cost of an off-plan property in Brazil.
Talk to a specialist
Want to see this applied to your case?
Instead of finishing the article and staying in theory, send us your situation on WhatsApp. We reply with the concrete next step.
Is the money left for the seller taxable capital gain?
No. Gross proceeds and pre-tax net cash measure the closing flow. Taxable gain requires a separate calculation based on the nature of the transferred right, disposal value, documented tax basis, admissible expenses, and any exemption. The amount should remain unknown until the required tax evidence is available.
Brazil’s Federal Revenue Service provides the GCAP process for calculating capital gains and requires supporting documentation. For individuals, Law 13,259 of March 16, 2016 establishes progressive rates beginning at 15% for the portion of gain up to R$5 million.
The law does not, by itself, settle the tax basis, exemptions, or characterization of a particular assignment. Its current validity and the taxpayer’s classification must be confirmed on the transaction date. See the Federal Revenue Service capital-gains guidance, accessed October 12, 2026.
The tax calculation uses reais for the relevant taxpayer and transaction, with the applicable month of disposal and tax year as its period. Rounding must follow GCAP and current Federal Revenue rules. If the tax basis, admissible costs, or exemption status is unknown, block the estimate and seek advice from a qualified accountant or tax lawyer.
What documents must a broker obtain before pricing the assignment?
A defensible estimate requires documents that can be reconciled to the proposed closing date. The file must show the contractual correction rule, current creditor balance, payment history, cost allocation, and required approvals. Missing evidence should be recorded as a condition that prevents final pricing or limits the quoted amount.
Obtain and review:
- the purchase agreement and amendments;
- the proposed assignment instrument;
- the creditor’s official balance statement;
- the original payment schedule and payment history;
- the contractual indexation clause;
- the current developer fee schedule;
- brokerage invoices and other cost evidence;
- certificates or statements for relevant debts;
- legal, tax, and credit approvals appropriate to the transaction.
The creditor should confirm buyer approval, consent requirements, debt assumption or simultaneous settlement, and release of guarantees. Legal counsel must examine form, registration, contractual restrictions, continuing liability, and whether the arrangement constitutes an assignment rather than a cancellation.
When should a broker refuse to quote a final net amount?
Do not quote a final net amount when the debt statement is outdated, the closing date is undefined, the correction rule is ambiguous, payments cannot be reconciled, seller expenses lack verified attribution, or tax treatment remains unresolved. A pending answer is safer than a precise figure without documentary support.
A conditional range may be used only when every variable, source, and limitation is explicit. Otherwise, keep the result open. Publishing an unsupported net amount can distort the seller’s expectations before negotiations begin.
Assignment and cancellation must also remain distinct. Law 13,786 of December 27, 2018 addresses contract termination for default in real-estate developments and land subdivisions. It does not provide a general pricing formula for a private assignment.
Compare the two routes in Distrato vs. Repasse: Which Exit Makes Sense for an Off-Plan Property?.
What is the final pricing rule?
An assignment is economically ready for pricing only when P, S, and D are documented, use the same closing date, and reconcile with the contractual payment flow. Calculate P minus S for gross assignment proceeds and P minus S minus D for pre-tax net cash. Keep tax and approvals separate.
This method does not remove uncertainty. It identifies it. Legal consent, credit approval, and tax treatment remain independent review gates even after the closing worksheet balances.
FAQ
How do I calculate the adjusted outstanding balance on an off-plan property?
Calculate the adjusted outstanding balance from the contract’s index variant, reference periods, lag rules, payment history, and allocation method. Because intermediate payments change the calculation, do not simply multiply an old balance by one accumulated index. Request the developer’s official statement for the intended closing date and reconcile every entry.
How does an off-plan property assignment work when money is still owed?
An assignment transfers the buyer’s contractual rights while the unpaid balance is assumed or settled under the transaction documents. Creditor consent may be required, as noted in São Paulo municipal guidance. The agreement should identify the seller’s payment, assumed debt, closing date, approval conditions, and each party’s expenses.
How do I work out what the seller actually keeps from the assignment?
Subtract the adjusted outstanding balance from the total negotiated price to estimate the seller’s gross assignment proceeds, using the same closing date for both amounts. Then subtract only documented expenses and debts contractually allocated to the seller. The result is pre-tax net cash, not automatically taxable capital gain.
Is the outstanding balance on every off-plan property adjusted by the INCC?
No, INCC cannot be assumed for every off-plan outstanding balance. The contract determines the index, variant, reference period, lag, and calculation method, and may change the index after completion or financing. FGV IBRE explains what INCC measures, but the developer’s calculation statement shows how the specific contract was applied.
Is an assignment the same as cancelling an off-plan purchase contract?
No, an assignment transfers contractual rights to another party, whereas cancellation ends the acquisition relationship under its applicable terms. Brazil’s Law 13,786/2018 primarily addresses contract termination for default and does not provide a universal assignment formula. Brokers should confirm the transaction’s legal structure, required consent, and continuing liabilities before advertising it.
Is paying for legal, tax, and debt verification worthwhile before listing the assignment?
Verification reduces the risk of quoting proceeds the seller will not actually receive. Before listing, compare the contract, current debt statement, payment history, developer fee schedule, and expense evidence. The appropriate review cost depends on the case, but unsupported assumptions can distort pricing, negotiations, tax expectations, and closing feasibility.
Can one calculation method be used for every off-plan assignment?
No universal calculation safely covers every off-plan assignment. The framework of negotiated price minus adjusted debt minus documented seller costs is an economic estimate, not a universal legal or tax rule. Applicability depends on the contract, closing date, creditor approval, local charges, debt mechanics, and separate legal, tax, and credit review.
Talk to a specialist
Have a real case to solve?
Message Imovitec on WhatsApp. We reply fast and already speak your context — no forms, no waiting.
Frequently asked questions
How do I calculate the adjusted outstanding balance on an off-plan property?
Calculate the adjusted outstanding balance from the contract’s index variant, reference periods, lag rules, payment history, and allocation method. Because intermediate payments change the calculation, do not simply multiply an old balance by one accumulated index. Request the developer’s official statement for the intended closing date and reconcile every entry.
How does an off-plan property assignment work when money is still owed?
An assignment transfers the buyer’s contractual rights while the unpaid balance is assumed or settled under the transaction documents. Creditor consent may be required, as noted in São Paulo municipal guidance. The agreement should identify the seller’s payment, assumed debt, closing date, approval conditions, and each party’s expenses.
How do I work out what the seller actually keeps from the assignment?
Subtract the adjusted outstanding balance from the total negotiated price to estimate the seller’s gross assignment proceeds, using the same closing date for both amounts. Then subtract only documented expenses and debts contractually allocated to the seller. The result is pre-tax net cash, not automatically taxable capital gain.
Is the outstanding balance on every off-plan property adjusted by the INCC?
No, INCC cannot be assumed for every off-plan outstanding balance. The contract determines the index, variant, reference period, lag, and calculation method, and may change the index after completion or financing. FGV IBRE explains what INCC measures, but the developer’s calculation statement shows how the specific contract was applied.
Is an assignment the same as cancelling an off-plan purchase contract?
No, an assignment transfers contractual rights to another party, whereas cancellation ends the acquisition relationship under its applicable terms. Brazil’s Law 13,786/2018 primarily addresses contract termination for default and does not provide a universal assignment formula. Brokers should confirm the transaction’s legal structure, required consent, and continuing liabilities before advertising it.
Is paying for legal, tax, and debt verification worthwhile before listing the assignment?
Verification reduces the risk of quoting proceeds the seller will not actually receive. Before listing, compare the contract, current debt statement, payment history, developer fee schedule, and expense evidence. The appropriate review cost depends on the case, but unsupported assumptions can distort pricing, negotiations, tax expectations, and closing feasibility.
Can one calculation method be used for every off-plan assignment?
No universal calculation safely covers every off-plan assignment. The framework of negotiated price minus adjusted debt minus documented seller costs is an economic estimate, not a universal legal or tax rule. Applicability depends on the contract, closing date, creditor approval, local charges, debt mechanics, and separate legal, tax, and credit review.
Imovitec
Turn data into next steps.
Take the Imovitec diagnostic and see where your best opportunities are.