Contemplated Consortium Credit for an Off-Plan Property: Aligning Credit, Construction and Cash Flow
A contemplated real estate consortium credit letter may fund an off-plan property in Brazil if the asset fits the contracted category and the administrator…
Imovitec · October 11, 2026
A contemplated real estate consortium credit letter may fund an off-plan property in Brazil if the asset fits the contracted category and the administrator approves the transaction. Contemplation does not make cash immediately available. Legal, contractual, documentary and guarantee requirements still apply.
For a broker advising a buyer, contemplation alone does not settle the decision. What matters is whether the credit, selected unit, developer’s schedule and buyer’s funds remain compatible through settlement, handover, registration and the final relevant payment.
Key takeaways
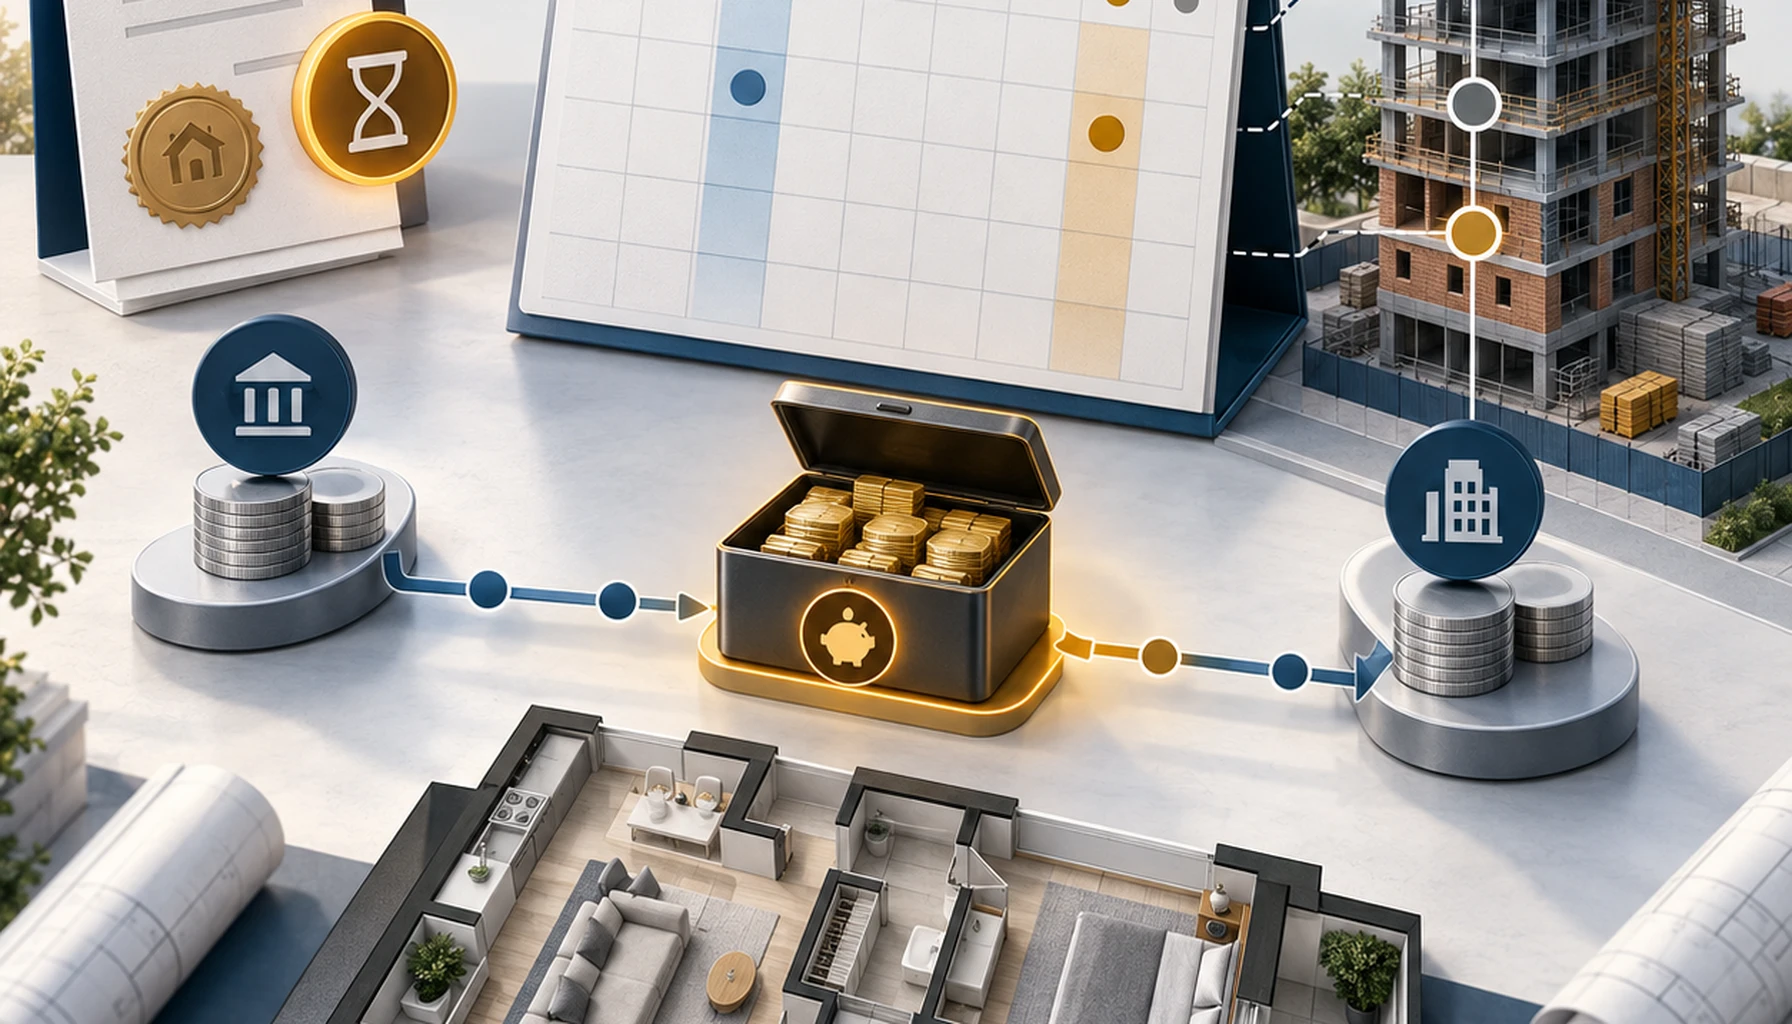
Contemplation gives the consortium member credit within the contracted category, but effective use still requires validation. Before signing, the broker should place three monthly calendars side by side: the administrator’s process, the developer’s charges and the buyer’s available cash. An unknown date or amount is not zero.
- The Central Bank of Brazil identifies off-plan property as a possible use of real estate consortium credit, subject to the contract and administrator requirements.
- The developer’s due dates do not determine when the administrator will release credit.
- The projection must include purchase payments, continuing consortium installments, contractual adjustments, accessory costs and a liquidity reserve.
- The National Construction Cost Index, known as INCC, measures residential construction costs, not property sale prices.
- Critical missing information must remain marked as pending and block the base case.
What does a contemplated credit letter mean?
A contemplated credit letter is credit attributed to a consortium member after contemplation for an eligible purchase in the contracted category. Within Brazil’s consortium framework, contemplation and effective use are separate events. The administrator must still assess the transaction, supporting documents, guarantees and other applicable conditions.
Articles 22 to 24 of Law 11,795/2008, published on October 9, 2008, establish the general rules on contemplation, supplier choice and credit value. The Central Bank of Brazil Consortium FAQ, consulted on October 11, 2026, provides public guidance on permitted uses.
Within the contractual category, the consortium member may choose the supplier and asset. That freedom does not remove valuation, registration, documentation or guarantee requirements.
But neither source guarantees approval of a particular unit or payment structure. Operational details depend on the consolidated regulation, including Resolution BCB 285/2023, the group contract and the administrator’s procedures. The current official text must be checked before publication or transaction approval because the research package did not recover a canonical consolidated URL or the exact provisions.
Can contemplated consortium credit buy an off-plan property?
Yes. Central Bank of Brazil guidance recognizes an off-plan property as a possible destination for real estate consortium credit. Approval, however, is not automatic. The administrator must confirm that the particular unit, development records, guarantees and proposed payment structure comply with the contract and current rules.
Before the proposal becomes binding, obtain written answers to four questions:
- Does the unit qualify under the buyer’s consortium contract?
- Which buyer, property and development documents are required?
- Which valuation, guarantee and payment conditions apply?
- To whom, when and under which conditions may payment be made?
What cannot be assumed? That every administrator pays according to construction progress, prepays the developer’s installments or accepts every off-plan unit. The approved sources establish no universal procedure.
The broker should also separate the advertised price, due dates and adjustment rules. This guide to reading a Brazilian developer sales table explains how to examine those elements before comparing units.
Why can the developer’s schedule and the credit fail to match?
A timing gap appears when the developer requires payment before the administrator releases the corresponding credit. It can also arise when the confirmed net credit falls short of the eligible settlement amount. This is a planning inference based on separate contractual processes, not a statutory forecast or a claim about every administrator.
Place three calendars on one monthly timeline:
- Consortium calendar: contemplation, validation, continuing installments and the possible use date.
- Development calendar: reservation, signing, construction installments, intermediate payments, handover and registration.
- Buyer cash calendar: verified own funds, accessory costs and liquidity reserve.
A developer may accept a negotiated arrangement, but Brazilian law does not require it to reshape its commercial schedule around an administrator’s process. Nor does contemplation guarantee disbursement on the date selected by the developer.
Only after these calendars have been reconciled with documented assumptions should the operation reach formal validation. See the related guide to connecting consortium credit, construction and cash flow.
How should the monthly cash-flow model be built?
The model should record required payments, confirmed inflows and the cumulative balance for each month from signing through handover, registration and the end of relevant obligations. It supports a decision; it is not a forecast. Missing dates or amounts must stay pending instead of silently becoming zero.
| Cash-flow item | Required evidence | Treatment if unknown |
|---|---|---|
| Developer payment | Purchase proposal or contract | Mark pending |
| Credit effectively released | Written administrator confirmation | Do not treat contemplation as cash |
| Consortium installment | Consortium contract and statement | Mark pending |
| Contractual adjustment | Contract clause and official index series | Do not substitute another index |
| Taxes, fees and registration | Dated local evidence | Treat as a potential own-funds need |
| Buyer funds | Verified available balance | Exclude unconfirmed resources |
In each month, the net cash requirement equals the developer payment, plus accessory costs and the reserve assigned to that period, minus credit effectively released and verified buyer funds then available. The unit is nominal Brazilian reais. No denominator applies.
Calculate the spreadsheet to the cent. Whole-real figures may appear in explanatory text only after that calculation. The projection covers signing, handover, registration and the end of relevant payments.
The cumulative monthly balance equals the prior balance, plus confirmed inflows, minus outflows. One missing date or amount blocks the base case.
At settlement, the closing gap equals the eligible property price and eligible costs, minus the net credit actually made available. Round the result to cents. Any expense without confirmed eligibility stays outside the credit and enters the model as a potential own-funds requirement.
For a wider cost review, see what the advertised off-plan price leaves out.
Talk to a specialist
Want to see this applied to your case?
Instead of finishing the article and staying in theory, send us your situation on WhatsApp. We reply with the concrete next step.
How should INCC adjustments enter the calculation?
Apply an INCC adjustment only when the contract identifies the index version, contractual base, reference period and lag. INCC-M, INCC-10 and INCC-DI use different collection windows and cannot be mixed. If a required input is absent, the adjusted amount must remain pending.
According to the FGV IBRE INCC methodology, consulted on October 11, 2026, the index tracks changes in residential construction costs in São Paulo, Rio de Janeiro, Belo Horizonte, Salvador, Recife, Porto Alegre and Brasília. Its basket includes materials and equipment, services and labor.
A key limitation sits here: INCC neither measures property sale prices nor reproduces the exact budget of a specific development. The purchase contract determines whether any version of the index applies.
In practical terms, the adjusted obligation is the contractual base multiplied by the accumulated factor specified in the contract. Build that factor by chaining each applicable periodic rate, multiplying every factor of one plus the relevant rate by the next.
Keep full precision throughout the chain. Round only the final monetary amount according to the contractual rule. The units are Brazilian reais and percentage rates; no separate denominator applies. The contract controls the period and lag. Never replace a missing index, month or rate.
What should the broker verify before signing?
The broker should verify transaction eligibility, the development’s legal file, the complete payment schedule and the buyer’s capacity to cover every amount outside the confirmed credit. Legal review, financial analysis and administrator approval address different risks.
One cannot replace another.
Consortium and administrator file
Request the consortium contract, current credit statement, contemplation record and written requirements covering eligibility, documents, valuation, guarantees and disbursement.
Article 24 of Law 11,795/2008 links the credit value to the good or service identified in the contract at the contemplation assembly date, plus proportional net financial earnings until use. The actual figure depends on the contract, the date and the earnings effectively credited.
The Central Bank of Brazil Consortium FAQ, consulted on October 11, 2026, provides public guidance on permitted uses.
Development and purchase file
Check the incorporation registration, purchase contract and mandatory summary information under the consolidated text of Law 4,591/1964. The existence and effects of a segregated estate regime, as well as cancellation consequences, depend on the actual registration and contract under Laws 10,931/2004 and 13,786/2018.
The guide to patrimônio de afetação and developer failure offers context. For a case-specific conclusion, the development’s registry evidence controls.
Financial file
Prepare a contractual case, a delay scenario and an adjustment scenario. Label each as a scenario, not a prediction.
The modeled minimum reserve is the absolute value of the largest negative cumulative balance across the projection. Express it in Brazilian reais and round it to cents in the spreadsheet. The period extends through handover, registration and the end of relevant payments. Its reliability depends entirely on documented dates, amounts and assumptions.
When is the transaction ready for formal validation?
The transaction is ready to be submitted, though not necessarily approved, when eligibility, payment mechanics and cash requirements are documented and remain viable under clearly labeled scenarios. A critical field without evidence must stay visible as unknown and prevent an unconditional recommendation to proceed.
Use this decision rule:
- Submit for validation when the administrator confirms eligibility and mechanics, the developer accepts the payment arrangement, and the buyer can cover every modeled gap.
- Renegotiate when viability depends on changing due dates, allocating payments differently or increasing the reserve.
- Pause when an essential document, value, adjustment clause, guarantee condition or disbursement date remains unknown.
A contemplated credit letter can support an off-plan purchase. Whether a particular transaction is workable depends on documented alignment among the credit, unit, construction schedule and buyer cash.
Sources and limitations
The primary references below were consulted on October 11, 2026. They establish general national rules and index methodology, but they do not approve a particular transaction. Each case still requires the current consolidated rules, its contracts, registry records, local costs and professional review.
- Presidency of the Republic, Law 11,795/2008.
- Central Bank of Brazil, Consortium FAQ and Resolution BCB 285/2023.
- Fundação Getulio Vargas, FGV IBRE, INCC methodology.
- Presidency of the Republic, Law 4,591/1964, Law 10,931/2004 and Law 13,786/2018.
Central Bank Circular 3,432/2009 was revoked effective July 1, 2024, and is not used here as a current operational rule. Legal review is required for the acquisition and guarantees. Financial review is required for the projection, adjustments and uncovered costs. The administrator must assess eligibility, documents, valuation, credit and collateral.
FAQ
How do I use a contemplated consortium credit letter to buy an off-plan property?
A contemplated credit letter can fund an off-plan property if the unit fits the contracted category and the administrator formally approves the transaction. Before signing, confirm eligibility, required documents, guarantees, payment method and disbursement timing in writing. Contemplation grants access to credit, but it does not mean immediate cash release.
What is a contemplated real estate consortium credit letter?
A contemplated real estate consortium credit letter represents the member’s right to use credit within the category defined by the consortium contract. Its effective use remains subject to legal, contractual, documentary and guarantee requirements. The credit amount and available balance must be confirmed with the administrator for the intended settlement date.
What’s the best way to align consortium credit with an off-plan property payment schedule?
The best approach is to compare the administrator’s validation and disbursement process with every developer payment due through handover and registration. Map the credit actually available, consortium instalments, contractual adjustments, accessory costs and the buyer’s own funds month by month. Any missing date or amount should remain pending, not be treated as zero.
Can consortium credit be used for any off-plan property in Brazil?
Consortium credit is not automatically valid for every off-plan unit. Brazilian rules permit real estate consortium credit to cover property in the contracted category, but the administrator must validate the specific asset and transaction. The developer must also accept the proposed payment arrangement, while registration, documentation and guarantee requirements still apply.
Can a contemplated credit letter be released according to construction milestones?
Construction milestone disbursement cannot be assumed without written confirmation from the administrator. No universal rule requires every administrator to release funds by work measurement, advance developer instalments or follow a commercial construction schedule. The broker should verify the approved disbursement format and compare it with the developer’s contractual due dates before commitment.
How can a broker assess whether the buyer will need additional cash?
Additional cash is required whenever payments and eligible costs exceed the credit effectively released plus the buyer’s available funds at each date. The analysis should include developer instalments, consortium payments, contractual adjustments, taxes, fees and a defined reserve. Unknown values must be tested as scenarios because they can conceal a future cash deficit.
Is the INCC enough to project the final cost of an off-plan purchase?
The INCC alone is not enough to project the final purchase cost. It measures construction cost changes and has different versions, collection windows and contractual applications. The projection must use the exact index, base date and lag stated in the purchase agreement, alongside all payments, fees and possible timing mismatches. Legal and financial review remains necessary.
Talk to a specialist
Have a real case to solve?
Message Imovitec on WhatsApp. We reply fast and already speak your context — no forms, no waiting.
Frequently asked questions
How do I use a contemplated consortium credit letter to buy an off-plan property?
A contemplated credit letter can fund an off-plan property if the unit fits the contracted category and the administrator formally approves the transaction. Before signing, confirm eligibility, required documents, guarantees, payment method and disbursement timing in writing. Contemplation grants access to credit, but it does not mean immediate cash release.
What is a contemplated real estate consortium credit letter?
A contemplated real estate consortium credit letter represents the member’s right to use credit within the category defined by the consortium contract. Its effective use remains subject to legal, contractual, documentary and guarantee requirements. The credit amount and available balance must be confirmed with the administrator for the intended settlement date.
What’s the best way to align consortium credit with an off-plan property payment schedule?
The best approach is to compare the administrator’s validation and disbursement process with every developer payment due through handover and registration. Map the credit actually available, consortium instalments, contractual adjustments, accessory costs and the buyer’s own funds month by month. Any missing date or amount should remain pending, not be treated as zero.
Can consortium credit be used for any off-plan property in Brazil?
Consortium credit is not automatically valid for every off-plan unit. Brazilian rules permit real estate consortium credit to cover property in the contracted category, but the administrator must validate the specific asset and transaction. The developer must also accept the proposed payment arrangement, while registration, documentation and guarantee requirements still apply.
Can a contemplated credit letter be released according to construction milestones?
Construction milestone disbursement cannot be assumed without written confirmation from the administrator. No universal rule requires every administrator to release funds by work measurement, advance developer instalments or follow a commercial construction schedule. The broker should verify the approved disbursement format and compare it with the developer’s contractual due dates before commitment.
How can a broker assess whether the buyer will need additional cash?
Additional cash is required whenever payments and eligible costs exceed the credit effectively released plus the buyer’s available funds at each date. The analysis should include developer instalments, consortium payments, contractual adjustments, taxes, fees and a defined reserve. Unknown values must be tested as scenarios because they can conceal a future cash deficit.
Is the INCC enough to project the final cost of an off-plan purchase?
The INCC alone is not enough to project the final purchase cost. It measures construction cost changes and has different versions, collection windows and contractual applications. The projection must use the exact index, base date and lag stated in the purchase agreement, alongside all payments, fees and possible timing mismatches. Legal and financial review remains necessary.
Imovitec
Turn data into next steps.
Take the Imovitec diagnostic and see where your best opportunities are.